France's presidential frontrunner detailed €140 billion in spending cuts and tax rises on Tuesday — and markets braced for fiscal chaos exhaled. The euro climbed off a 16-month low and French bond yields fell. But the plan's contradictions, from a pension rollback to a clash with EU treaties, are already showing.
PARIS — The Le Pen deficit plan landed on Tuesday with the one thing French markets have been starved of for months: specifics. National Rally leader Marine Le Pen unveiled a detailed programme of €140 billion in spending cuts and tax rises, the follow-through to the "golden rule" budget framework she sketched on October 2. Investors, who had spent weeks pricing in the worst — dumping the euro to a 16-month low and pushing the French-German bond spread to its widest since the 2011 euro crisis — responded within hours. The euro rose 0.2 percent to $1.1244, French 10-year yields fell 11 basis points to 4.761 percent, and the dollar index slipped 0.2 percent to 102.004, according to LSEG and Tradeweb data cited by the Wall Street Journal and Barron's.
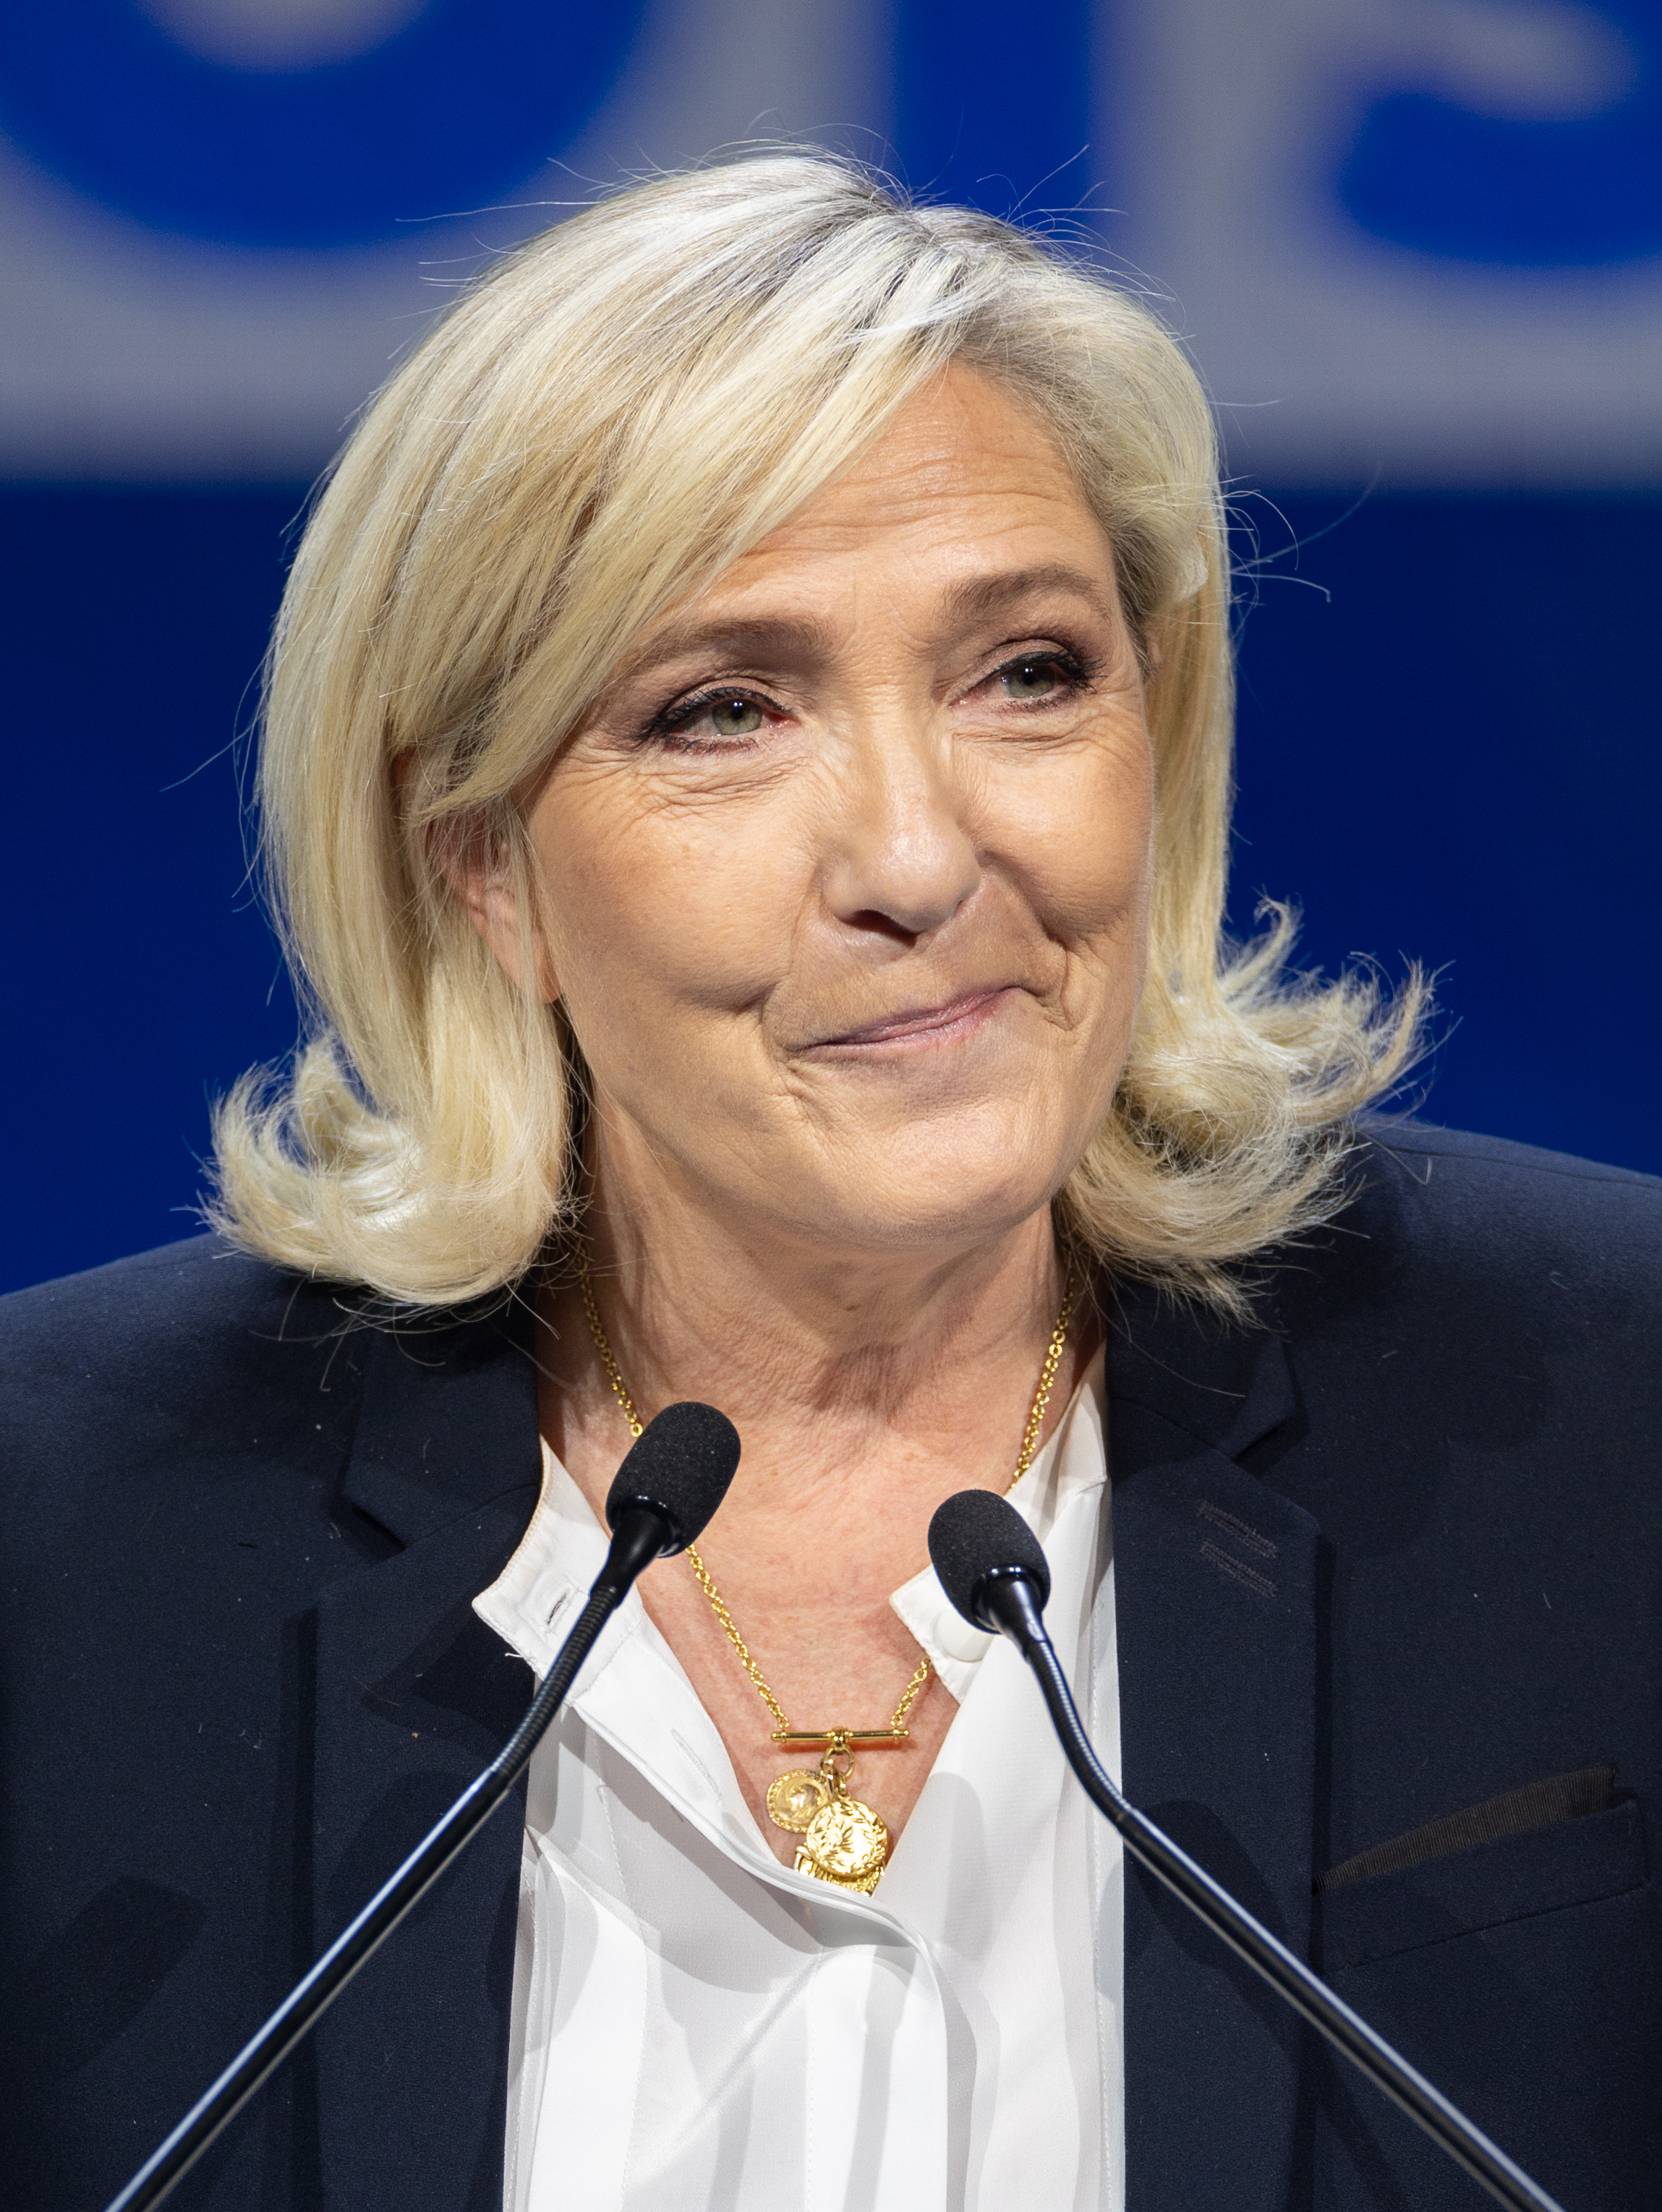
It is a remarkable political inversion, and it is worth sitting with for a moment: the candidate long cast by markets as the fiscal risk is now campaigning as the fiscal disciplinarian — and markets, at least for a day, are buying it. Whether they keep buying it will shape not just the April 18–May 2 presidential election, in which Le Pen leads the polls for both rounds, but the trajectory of the eurozone's second-largest economy for a decade.
France's public finances are the eurozone's slow-burning emergency. The deficit sits at 5.4 percent of GDP — nearly double the EU's 3 percent ceiling — and public debt stands at 119 percent of GDP against a treaty target of 60 percent. For years, Paris papered over the gap with the implicit guarantee that France is too big to be disciplined. That guarantee expired in stages: first when investors started demanding a premium to hold French bonds, then on Friday, when the government's 2027 budget bill offered so little relief that the spread between French and German 10-year yields blew past 150 basis points — its highest since late 2011, when the eurozone itself looked mortal.
That is the context in which a Le Pen fiscal plan moves markets. Investors had cut exposure to French assets precisely because they doubted that whoever wins next year could bring the deficit under control, as Reuters reported on October 2. A detailed €140 billion programme from the polling frontrunner doesn't resolve the doubt — but it replaces a vacuum with arithmetic, and markets will always price arithmetic over a vacuum. The 11-basis-point fall in French yields on Tuesday is the sound of risk being repriced, not removed.
There is a second, structural significance. The euro's slide to a 16-month low of $1.1160 on Monday and the dollar index's climb to a near-18-month high of 102.535 were not just about France — they reflected a broader flight into the dollar. But France was the European accelerant: the continent's second economy, politically adrift, fiscally unanchored. A credible path to deficit reduction in Paris would remove one of the two great weights on the single currency. Tuesday's bounce suggests traders are at least entertaining the possibility.
What she actually announced
The headline number is €140 billion: a package of spending cuts and tax rises that Le Pen says will put France's finances on a sustainable path. It is the detailed version of the framework she laid out on October 2 in the French newspaper L'Opinion — and the numbers have grown teeth since then.
The architecture is a "golden rule," modeled explicitly on Germany's debt brake. Le Pen proposes putting it to a referendum, which would bind lawmakers in annual budget legislation with only tightly limited exceptions: the deficit would have to fall by at least half a percentage point of GDP every year, taking it from 5.4 percent this year to 2.9 percent in 2032, the end of the next presidential term. It would keep falling toward balance until the debt ratio — 119 percent today — returns to 60 percent. A larger deficit would require a three-fifths parliamentary majority; a second consecutive exception would trigger another referendum. The High Council of Public Finances would validate the assumptions behind each year's ceiling, and the Constitutional Council could reject "insincere" budgets.
On October 2, Le Pen had spoken of €125 billion in savings over five years, net of tax cuts, and called those figures a minimum — promising that the full programme, to be outlined on Tuesday, would cut spending faster. The €140 billion package unveiled today is that promise kept, at least on paper. She was explicit that neither economic growth nor tax rises alone could repair the finances — a line aimed as much at her critics as at her base.
The golden rule, explained
For readers outside fiscal-policy circles: a golden rule is a constitutional or quasi-constitutional speed limit on borrowing. Germany's debt brake, the acknowledged model, caps the federal structural deficit at 0.35 percent of GDP and is widely credited — and blamed — for Berlin's fiscal rectitude. Le Pen's version is more aggressive in its glide path (half a point a year is a brisk pace of consolidation) but softer in its enforcement, relying on referendums and supermajorities rather than a hard constitutional cap. The referendum mechanism is characteristically Le Pen: it converts a technocratic constraint into an act of popular sovereignty, making the rule politically harder to repeal than a mere statute.
The market reaction, in context
Tuesday's moves were modest in absolute terms — a fifth of a percent on the euro, 11 basis points on French yields — but significant in direction. Consider the before-and-after:
Before: the euro at $1.1160, its weakest in 16 months. The dollar index at 102.535, its strongest in nearly 18 months. The French-German 10-year spread above 150 basis points, a level not seen since the autumn of 2011, when Silvio Berlusconi was falling and the eurozone's survival was an open question. Investors had, in Reuters' phrase, "cut exposure to French assets" — a polite way of saying they were running.
After: the euro at $1.1244, French yields at 4.761 percent, the dollar index at 102.004. Not a reversal — a reprieve. The spread remains historically wide; the euro remains far below its recent highs. What changed is the narrative: from "no one in Paris has a plan" to "the frontrunner has published one." Markets are forward-looking machines, and they had been pricing a future in which French fiscal policy was made up meeting by meeting. A published, referendum-backed consolidation path — even one full of holes, as critics will note — is a different future to price.
The honest caveat, and it matters: one day does not make a trend. Currency desks will want to see whether the euro holds its gains through the week's U.S. data — the Federal Reserve's September meeting minutes land Wednesday — and bond desks will want to see the plan survive contact with detailed scrutiny. Relief rallies built on political announcements have a well-documented half-life.
How we got here: France's fiscal hole
France did not arrive at a 5.4 percent deficit by accident. Successive governments spent through the pandemic, the energy crisis, and a long political stalemate, while revenues sagged and the pension system — among Europe's most generous — kept compounding its liabilities. The 2027 budget bill, unveiled last week, was supposed to signal seriousness; instead it offered so little that the bond market revolted, widening the spread past 150 basis points on Friday.
Politically, the vacuum has been total. President Emmanuel Macron, constitutionally barred from a third consecutive term, presides over a fractured parliament. Into that vacuum stepped Le Pen, who has spent the last two years doing something her critics find more alarming than her old platform: moderating. She dropped the long-standing pledge to pull France out of the eurozone and restore the franc — once the single most market-terrifying item in her programme — and now promises to reform the bloc from within. The fiscal-discipline pivot is of a piece with that strategy: broaden the appeal, neutralize the fear, win the center-right voters who decide French runoffs.
The contradictions — and what critics say
A plan this ambitious invites arithmetic questions, and the critics have them ready. Presenting both sides fairly:
The pension problem. Le Pen has pledged to undo Macron's deeply unpopular pension reform, rolling the retirement age back to 62 from 64. Analysts note this would add significant structural expense to an already strained pension system — working directly against the deficit-reduction math. Her supporters counter that the savings programme is sized to absorb it, and that the €140 billion figure is a floor, not a ceiling. But no detailed costing reconciling the two pledges has been published.
The EU treaty problem. A key pillar of the savings — halving France's financial contribution to the European Union budget — would, analysts say, violate EU treaties, invite legal retaliation from Brussels, and trigger severe friction with the very bloc Le Pen now promises to reform from within. Supporters frame it as negotiating leverage: Paris pays in more than it gets back, and a credible threat sharpens the bargaining. Critics call it the return of the old Le Pen by another door — confrontation with Brussels dressed as fiscal prudence.
The composition problem. The €125 billion in savings is described as relying heavily on curbing immigration and reducing social benefits for non-citizens — measures whose fiscal yields are disputed and whose implementation would face legal and administrative obstacles. And the plan's internal politics are unsettled: Jordan Bardella, Le Pen's running mate and likely prime minister, has pushed a more liberal, pro-business line to court mainstream industry, occasionally clashing with the party's old-guard economic advisers who favor state intervention and protectionism. A plan is only as coherent as the coalition that must implement it.
None of this means the plan is unserious — €140 billion with a referendum-backed enforcement mechanism is the most detailed fiscal programme any French frontrunner has published in years. But "most detailed" and "fully costed" are different bars, and the bond market, having been burned before, will apply the second one.
Who gains, who loses
Holders of French assets gain first. Bondholders saw yields fall and prices rise on Tuesday; euro longs got a reprieve. If the plan sustains credibility, the biggest winners are French taxpayers, who currently fund a risk premium — that 150-basis-point spread — that flows straight to investors as extra borrowing cost.
The Macron succession field loses ground. Every day the fiscal conversation is about Le Pen's plan is a day it isn't about the government's. With the president barred from running again, the center's candidate inherits both the fiscal mess and the political cost of the 2027 budget bill that triggered Friday's selloff.
Brussels faces a dilemma. A French president elected on a mandate to halve EU contributions and bind budgets by referendum would arrive in the European Council as both a reformer and a wrecking ball. The Commission's response — accommodation or confrontation — would set the tone for EU fiscal politics for years.
French public-sector workers and benefit recipients face the sharp end. €140 billion in spending cuts and tax rises, however distributed, means real retrenchment: fewer public jobs, leaner benefits, higher taxes somewhere. The plan's popularity in the polls will be tested against its distributional reality the moment the detailed line items appear.
What happens next
Three things to watch. First, the scrutiny phase: economists and the bond market will now do what they do — stress-test the numbers, starting with the pension rollback and the EU-contribution cut. The spread's next move will tell you whether Tuesday's relief has legs.
Second, the campaign: with the election set for April 18–May 2 and Le Pen leading in the polls, rivals must now answer her plan with plans of their own. The fiscal debate she has forced is, win or lose, her achievement — no frontrunner in recent French history has made deficit reduction the centerpiece this early.
Third, the referendum question. A golden rule put to popular vote would be a first for a major eurozone economy — fiscal policy by plebiscite. If it passed, France would have the continent's most democratically entrenched budget constraint. If it failed, the plan's enforcement mechanism collapses, and with it the market credibility Tuesday's rally was built on. Either way, the euro's 16-month low may come to be seen as the moment France's fiscal reckoning finally got a date.
Sources: Wall Street Journal, Barron's (LSEG and Tradeweb market data); Reuters, October 2 (golden-rule framework, polling, spread data); Continuum Economics (policy context and analysis).