Ray Dalio AI bubble warning
The Bridgewater founder told the Forbes Global CEO Conference in Singapore that debt-fueled AI investment is nearing a bursting point, just as the S&P 500 and Nasdaq hit record highs and borrowing costs climbed to multi-decade highs.
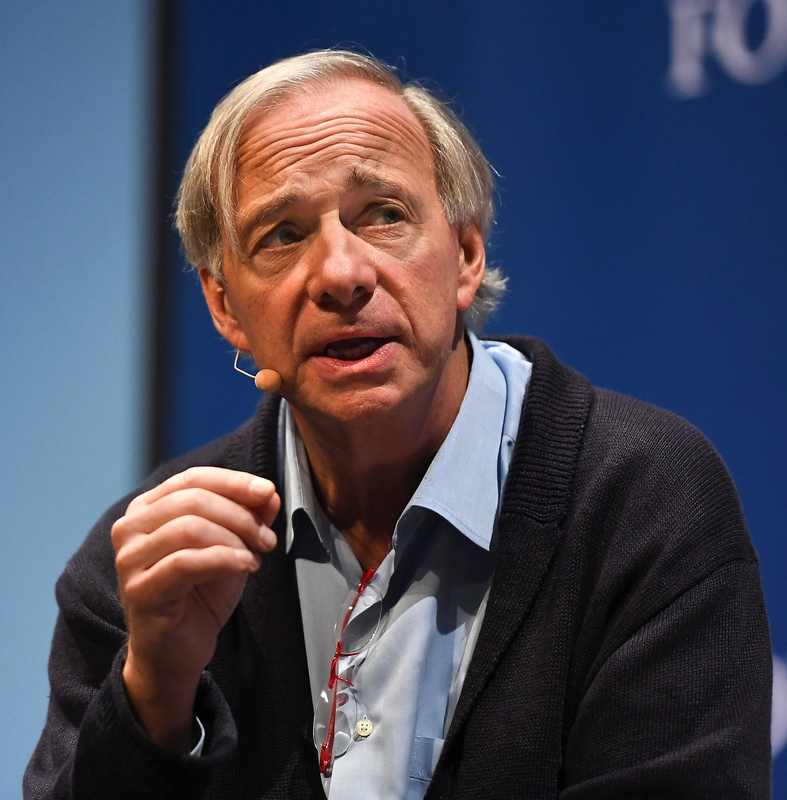
The Ray Dalio AI bubble warning landed Wednesday in Singapore with the weight only Dalio's track record carries. Speaking at the Forbes Global CEO Conference, the Bridgewater Associates founder told executives that artificial intelligence is a “classic bubble” nearing the point where it bursts, driven by a large amount of debt being raised to fund AI investment and rising interest rates that could eventually pop it. “We are in the part of the cycle that is before that but approaching that,” Dalio said, adding, “I think we're close to that.”
The remarks came in the same week that the S&P 500 and Nasdaq 100 closed at record highs, and as other heavyweights on Singapore's conference stages — Temasek chief investment officer Rohit Sipahimalani, Franklin Templeton CEO Jenny Johnson and Bangkok Bank executives — debated the question now defining global markets: how long the AI rally can last.
Why this matters
Dalio's specific claim is not that AI is fake. It is that great technology can still be a terrible investment at the wrong price. The distinction matters because market gains have concentrated in a small group of large technology companies while the industry spends hundreds of billions of dollars on chips, data centers and power — with an increasing share of that buildout financed through debt.
Higher bond yields are pushing up the cost of the money funding that expansion. When the founder of the world's largest hedge fund warns that the financing structure resembles past speculative cycles, asset managers listen. The warning arrived while the indices were still climbing, which is precisely when late-cycle risks are easiest to dismiss.
What Dalio actually said
As Reuters and IANS reported, Dalio's core argument is mechanical: a large amount of debt is being raised to fund AI investment, and higher interest rates could eventually cause the bubble to burst. He drew a sharp line between “how terrific a technology is and how terrific an investment is.” A technology can transform the world while its stocks still collapse.
Dalio also named other possible triggers, including wealth taxes and pressure on wealthy investors to convert unrealized gains into cash. “Everybody says ‘I'm worth a billion dollars’ but OK, try to spend that,” he said. Selling assets to realize wealth can put pressure on richly valued markets. He has been developing the case for months, describing AI as showing “classic signs” of a bubble in August and connecting it to a wider cycle of deficits, debt and weakening demand for U.S. bonds.
The debt engine behind the AI buildout
The reason Dalio's warning bites is the financing beneath the boom. The AI infrastructure race increasingly includes debt-financed data-center construction, leveraged chip purchases and circular deals in which revenue is recognized around the same transaction loop. The concentration risk is visible in the indices: record closes powered by a narrow set of mega-cap technology names while much of the market lags.
At the same time, global bond yields are at or near multi-decade highs. Every new data center costs more to finance, and every dollar of projected AI revenue must clear a higher hurdle. Dalio's argument is not that spending on AI is irrational. It is that debt-fueled spending near the top of a rate cycle has the textbook structure of bubbles from railroads to dot-coms. The reported $40 billion SpaceX financing for Nvidia chips illustrates how enormous the capital requirements have become, while Finland's halt to work on two Google data centers shows that financial and physical constraints can arrive together.
What the numbers say
The valuation comparison is striking. Reuters reported the S&P 500's cyclically adjusted price-to-earnings ratio, or Shiller CAPE, at roughly 41 — above its peak before the 1929 crash and just below the record 44 reached in 2000 before the dot-com bust. The 10-year U.S. Treasury yield approached its highest level in nearly a quarter century this week, the headwind Dalio says will eventually bite the leveraged AI trade.
The timing carries an irony that the Singapore panels themselves noted: equity valuations keep rising on optimism about future technology earnings even as the cost of building the AI future rises beneath them. Record highs and bubble warnings are not contradictory. They often arrive together because the same optimism that drives a market higher also makes its financing more fragile.
Who wins, who loses
If Dalio is right, the relative winners are the hedgers. He says his protection comes from spreading bets across 10 to 15 uncorrelated return streams and shorting debt. Disciplined value investors and holders of less rate-sensitive assets benefit if borrowing costs remain elevated and AI revenue arrives more slowly than markets expect.
The losers in that scenario are late buyers who paid record valuations, companies that leveraged up for data-center capacity and the broader economy if a market correction lands alongside fiscal strain. But the counter-case was voiced on the same Singapore stages. Franklin Templeton's Jenny Johnson argued that AI has not yet produced broad productivity gains for U.S. companies — implying that the payoff may still lie ahead rather than the industry being finished. Temasek's Sipahimalani called the AI narrative “the biggest risk to the market” while conceding that “right now, it seems very strong.” The internet survived the dot-com bust; AI could survive a repricing of its own.
What happens next
Watch three things. First, interest rates: Dalio's trigger is higher rates biting leveraged borrowers. If central banks ease, the bubble gets more air; if yields keep climbing, the squeeze tightens. Second, earnings: the AI trade's justification is real revenue from real products. If productivity gains begin appearing across 2027 results, today's valuations gain support. If end users do not see sufficient returns, the narrative weakens.
Third, watch financing structures. Debt-heavy deals across the AI supply chain are where forced selling begins when cash flow misses projections. Dalio has described bubbles as matters of degree rather than simple on-off calls, so no single event must “prick” this one. The structure of his argument is nevertheless clear: the boom's financing, not its technology, is the fragile part — and October's record highs are when that fragility is easiest to ignore.
Sources
- Reuters: Existential threats join bubble fears as AI mood sobers at Singapore forums (Oct. 7, 2026)
- IANS via hi INDIA: AI is a “classic bubble” nearing burst — Ray Dalio (Oct. 7, 2026)
- Seeking Alpha: Dalio says markets are close to the point where an AI bubble could burst
- The Cryptonomist: Ray Dalio says the AI investment bubble is nearing a breaking point