Meloni Babis EU carbon market reform is moving from national complaint to a coordinated European bid: Italy and Czechia want lower energy costs, a looser carbon market, a temporary methane-rule pause and a later start for ETS2. The decisive distinction is that officials have confirmed the agenda, but the package remains a proposal rather than an enacted change.
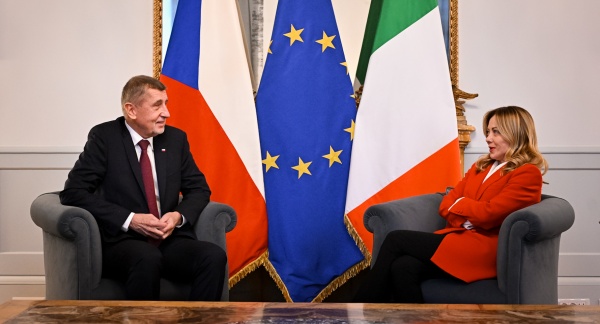
Italian officials speaking before the leaders' meeting said Meloni and Babis would seek agreement on a joint plan to contain energy costs and overhaul the European Union's Emissions Trading System. They also said Rome and Prague want a temporary suspension of the bloc's methane regulation and a postponement of ETS2, the separate carbon market for fuel used in buildings and road transport. Their intended venue for escalation is the European Council meeting on October 15–16. Reuters reported the officials' account.
That is the news. What it means is more complicated. Europe is now deciding whether a carbon price built to become more binding in moments of scarcity should instead become more flexible precisely when scarcity hurts. The answer will shape industrial power bills, household fuel costs, clean-energy investment and the credibility of a system that works only if companies believe tomorrow's permits will remain scarce.
Why this matters: affordability versus a credible carbon price
The EU ETS is not a surcharge pasted onto a bill by Brussels. It is a cap-and-trade market. Power generators and industrial installations must surrender one allowance for each tonne of carbon dioxide they emit; the number of allowances falls over time. Firms that can cut emissions cheaply have an incentive to do so, while those that cannot buy permits. The price is the signal.
But a signal can become a shock. The conflict with Iran has driven fuel prices higher and forced governments to search for relief. Reuters reported on September 23 that the ETS accounts for about 11% of industrial electricity bills across the EU on average. That burden can be far higher in fossil-heavy power systems such as Poland's, because more carbon must be bought for each unit of electricity produced. In systems rich in nuclear and renewable generation, the direct carbon component is lower.
The political case from Rome and Prague is therefore straightforward: when imported fuel becomes more expensive, policymakers should not allow a second, policy-driven price to intensify the same squeeze. The counterargument is equally direct. If officials release more permits whenever energy becomes painful, companies may stop treating carbon scarcity as durable and defer the investments the market was designed to accelerate.
The four-part Meloni-Babis proposal
The announced package contains four related but legally distinct requests. Bundling them strengthens the political narrative, but it does not mean they will move through Brussels together.
- Lower energy costs. This is the umbrella objective, not yet a single policy instrument. Italy and Czechia want EU action that eases pressure on industry and consumers during the current fuel-price surge.
- Overhaul the existing ETS. The aim is to soften price spikes without abandoning the carbon market. The immediate debate concerns how many spare allowances can be retained and released, and when.
- Temporarily suspend methane import rules. Rome and Prague argue that requirements taking effect from January could narrow the pool of alternative gas suppliers, raise compliance costs and complicate security of supply.
- Postpone ETS2 beyond 2028. The new market would put a carbon price on fuel supplied for buildings, road transport and certain smaller sectors. The two governments say its launch could add to heating and mobility costs during an already severe energy shock.
Those objectives pull on different legislative threads. The EU methane regulation and the directive underpinning ETS reform and ETS2 are existing law. A summit can set political direction, but it cannot by itself erase legal obligations. Durable changes would still require formal proposals and agreement through the EU's lawmaking process.
EU ETS reform in 2026: the reserve is already being renegotiated
The Rome meeting lands in the middle of a live negotiation rather than at its beginning. On September 23, EU ambassadors agreed to stop cancelling excess carbon allowances until 2030. Under their approach, the permits would remain in the Market Stability Reserve as a buffer that could later be released to counter price spikes. From 2031, cancellation would resume above a new 800 million-permit threshold, which would then decline over time.
The existing mechanism is much tighter. The European Commission's official Market Stability Reserve explainer says allowances above a 400 million threshold have been invalidated annually since 2024. It also explains that the reserve automatically withdraws allowances when too many circulate and releases them when supply becomes tight. In other words, EU market stability reserve permits are already governed by a rules-based thermostat; the argument is over where to set it.
The European Parliament has not taken the same position as member states. As summarized by Green Central Banking, lawmakers voted to retain automatic cancellation while lifting the cap from 400 million to 650 million allowances. Parliament also backed stronger price-containment tools for ETS2. The emerging compromise zone is visible: preserve scarcity, but make the reserve larger and the emergency release valve easier to use.
How EU carbon permit prices reach an electricity bill
Carbon permits are traded because compliance needs differ. A utility burning coal must buy more allowances than a gas plant for the same power output, while a wind farm buys none for generation. The expected future supply of allowances, fuel prices, industrial output, weather and hedging demand all influence the market price. In markets where fossil generators often set the marginal wholesale power price, some carbon cost can affect electricity prices beyond the specific plant that bought the allowance.
That does not mean the carbon market caused the current energy shock. The September 23 reporting explicitly described the Iran-driven fuel surge as the main source of the pressure and the ETS as a secondary contributor. This distinction matters because releasing carbon permits cannot manufacture gas, reopen shipping lanes or reverse a crude-oil shock. It can reduce one component of the bill, but not the geopolitical one.
Politicians in several countries have also blamed financial speculation for amplifying EU carbon permit prices. Financial investors do participate in the market, and their positioning can add liquidity as well as volatility. Yet a high or fast-moving price is not proof of manipulation. The durable drivers are the emissions cap, expected permit supply, demand from regulated firms and expectations about future policy. Claims of excessive speculation should therefore be tested against market data rather than treated as established fact.
EU methane regulation and gas-supply risk
The methane request is the package's most direct appeal to energy security. The regulation is designed to improve measurement, reporting and verification of methane emissions, reduce leaks in the EU energy sector and impose requirements on imported fossil fuels. Methane is a powerful greenhouse gas, and cutting leaks can deliver rapid climate benefits.
Italy and Czechia argue that applying new import requirements from January could make some alternative suppliers harder to use at a moment when Europe needs flexibility. That claim requires careful separation of compliance friction from physical scarcity. Reporting and verification can raise costs or exclude poorly documented supply. But a blanket pause may also reduce the incentive for exporters to measure and control leaks. The policy choice is not simply gas versus climate; it is whether temporary flexibility can be narrowly designed without turning into indefinite exemption.
Could ETS2 be postponed beyond 2028?
ETS2 is politically combustible because its costs are closer to the kitchen table. Rather than covering large power plants and factories, the system applies upstream to fuel suppliers serving buildings, road transport and certain additional sectors. Suppliers surrender allowances, but the economic cost can be passed through to heating and fuel prices.
The Council's June 2026 account says ETS2 is to become fully operational by 2028 and is intended to help cut emissions in covered sectors by 42% from 2005 levels by 2030. It also records a provisional agreement on reserve measures meant to cushion sharp price swings. Meloni and Babis are asking whether that cushion is enough—or whether the launch itself should move.
For households, a delay would defer a visible new cost during an inflationary period. For policy credibility, however, delay is not neutral. Buildings and transport are difficult sectors to decarbonize, and their capital stock turns over slowly. If governments postpone the price signal without accelerating insulation, heat-pump adoption, public transport or cleaner vehicles, Europe can lose time rather than merely change the sequence.
Who could win
Energy-intensive industry would be the clearest near-term beneficiary of more flexible permit supply. Steel, chemicals, cement, glass and other sectors facing global competition could see lower compliance or power costs, particularly where fossil generation remains dominant.
Households exposed to ETS2 would gain from a postponement if suppliers would otherwise pass allowance costs into petrol, diesel or heating fuel. The benefit would be most immediate for people who cannot quickly change cars, boilers or housing efficiency.
Italy, Czechia, Poland and similarly exposed economies would gain political room to manage the shock. Their industries and energy systems differ, but all have pressed for greater attention to competitiveness and affordability. The push also gives national leaders a tangible answer to voters who see climate policy through bills rather than long-run models.
Who could lose—and what could go wrong
Climate advocates will argue that weaker scarcity means a weaker incentive to replace high-carbon equipment. A carbon market does not need the highest possible price to work, but it does need a sufficiently predictable one. Repeated political intervention can turn a cap into a soft ceiling.
Clean-energy investors face a related risk. Renewable power, efficiency upgrades, electrified industrial processes and low-carbon fuels compete partly on the avoided cost of emissions. If the expected carbon price falls or becomes subject to election-cycle intervention, project economics worsen and financing becomes harder.
Governments could also trade a short-term bill reduction for a long-term fiscal problem. ETS auction revenue helps fund modernization and transition measures. Fewer auctioned allowances or lower prices can mean less money for the investments that reduce future exposure to imported fuel.
The sharpest danger is not a one-off adjustment. It is a precedent in which every commodity shock prompts a loosening of the cap. That would preserve dependence on fossil fuels while weakening the mechanism meant to reduce it. Recent coverage of Europe's alarm over a possible U.S. diesel export restriction and Brent's move around $100 as Saudi pipeline flows resumed shows why policymakers feel pressure. It also shows why carbon-market changes cannot substitute for supply diversification.
What happens at the October 15–16 EU summit
Three outcomes are plausible. The first is a targeted compromise: leaders endorse larger buffers, faster price-triggered releases and transition support while preserving the declining emissions cap. This is the easiest bridge between the Council and Parliament positions.
The second is delay without deep dilution. ETS2 could be moved back while the existing industrial ETS remains mostly intact. That would give governments time to strengthen household compensation and lower fuel-price exposure, but only if the delay comes with a funded implementation plan.
The third is a broader rollback: suspending methane obligations, slowing permit scarcity and delaying ETS2 as a single political response to high energy costs. That would deliver the largest immediate relief signal—and create the greatest uncertainty for investors and the EU's climate trajectory.
The most likely path is negotiation, not wholesale acceptance. Parliament's 650 million-permit position and member states' 800 million threshold after 2030 leave room for a numerical bargain. ETS2's existing price protections can be strengthened. Methane rules may attract limited transitional flexibility rather than a clean suspension. The summit can accelerate those compromises, but legislation still has to pass through the institutions.
The central test is whether leaders distinguish delay from dilution. A carefully bounded pause can protect households and factories while preserving the long-run signal. A permanently softer cap would change the economics of Europe's transition. Meloni and Babis have put affordability at the center of the October agenda; Brussels must now decide how much policy credibility it is willing to spend to buy relief.
Sources
- Reuters: Italy and Czech Republic to call for softer EU rules on carbon permits, energy supply
- Reuters: EU countries back carbon-market changes to curb price spikes
- European Commission: Market Stability Reserve
- Council of the EU: ETS2 Market Stability Reserve provisional agreement
- Green Central Banking: EU climate and carbon-market roundup
- EUR-Lex: Regulation (EU) 2024/1787 on methane emissions
- EUR-Lex: Directive (EU) 2023/959 amending the ETS framework