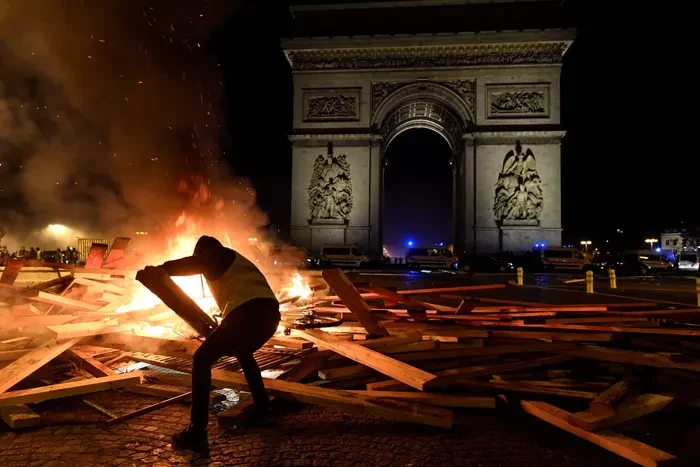
France bond yields jumped on Monday as a weekend of cost-of-living unrest met a bond market already primed to punish French fiscal drift: the 10-year yield rose about 13 basis points to roughly 4.9 percent, the spread over Germany widened to 146 basis points, and the CAC 40 fell about 1.5 percent.
Track it live: Live markets tracker
The numbers: a bad morning in a bad month
Each figure in Monday's sell-off carries a comparison that makes it worse. The 10-year yield at roughly 4.9 percent is not merely high; it is at levels last associated with the pre-euro era's end and the sovereign debt crisis's approach — the highest since 2002, per the reporting. The 146-basis-point spread over Germany is a two-week high, but the more telling number is the early-October peak near 160 basis points: Monday's widening is a move back toward the worst of it, not a spike from calm. The equity market told the same story in company form. The CAC 40 fell about 1.4 to 1.5 percent, led by the banks that hold French sovereign paper: Societe Generale down 2.7 percent, BNP Paribas and Credit Agricole around 2.5 percent. LVMH fell 2.2 percent after looting reached luxury retail. And Carrefour's chief executive Alexandre Bompard supplied the statistic that connected the trading floor to the street: 50 of the supermarket group's stores looted, with repair costs above €10 million. The euro slipped to about $1.1224, the currency market's small, precise shrug.
The politics the market is pricing
Prime Minister Sebastien Lecornu did not rule out a state of emergency and asked some local authorities to impose curfews — the vocabulary of a government managing disorder while it negotiates a budget the bond market is already grading. Unions have called a nationwide strike for November 5, which converts Monday's sell-off from a reaction into a position: traders are not only pricing what happened over the weekend, they are pricing the probability that France cannot pass, fund and defend an austerity budget through a winter of strikes. Deutsche Bank's Jim Reid and Gavekal's Louis-Vincent Gave were quoted across Monday's coverage making versions of the same point — that French risk is now fiscal and political simultaneously, with the 2027 presidential election already casting its shadow over every budget line. When a country's borrowing premium is set by the interaction of street, parliament and succession, spreads stop mean-reverting on good data; they need a political event to close, and no political event is scheduled.
Why this matters
France matters to markets out of proportion to one bad Monday because of where it sits: too big for the eurozone's rescue machinery to treat casually, too indebted for its politics to ignore the machinery's terms. A 146-basis-point spread is not a crisis — Italy has lived for years at levels that would panic Paris — but the direction and the driver are what strategists watch. Italy's premium prices a known fiscal story told by a stable government; France's now prices an unstable political story attached to a deteriorating fiscal one, which is the combination that historically widens fastest. There is also a feedback loop the weekend made visible: unrest raises the political cost of consolidation, failed consolidation raises borrowing costs, borrowing costs consume the budget room that might have bought social peace. Every basis point of the 146 is, in that sense, a small forecast that the loop continues. Signal Post News's coverage of the weekend unrest and its aftermath and of the protests that preceded it sets out the street-level sequence the market is now pricing.
What happens next
Three dates organise the risk. The November 5 general strike is the near one: a large turnout with renewed disorder would test whether 146 basis points was a warning or a waypoint toward the early-October 160. The budget calendar is the structural one: every amendment that softens consolidation to survive parliament widens the fiscal gap the spread is measuring. And 2027 is the long one — Reid's and Gave's point — because markets have begun pricing French political succession risk two years early, an unusual and expensive habit. Watch, too, the banks: if SocGen and BNP continue to underperform the sovereign story rather than the earnings story, the sovereign-bank loop that defined the euro crisis's worst chapters is reassembling in its second-largest economy. Track the spread and the CAC live on the markets tracker.
Sources: Reuters and Bloomberg, October 19, 2026 (10-year yield up ~13bp to ~4.9%, highest since 2002, near the 4.99% early-October high; French-German 10-year spread at 146bp, a two-week high, versus ~160bp in early October; CAC 40 down ~1.4–1.5%; Societe Generale −2.7%, BNP Paribas and Credit Agricole ~−2.5%, LVMH −2.2%; euro ~$1.1224; unions' November 5 strike call; Lecornu not ruling out a state of emergency; curfew requests; Jim Reid of Deutsche Bank and Louis-Vincent Gave of Gavekal quoted). Carrefour CEO Alexandre Bompard, statement reported October 19, 2026 (50 stores looted, repair costs above €10 million).