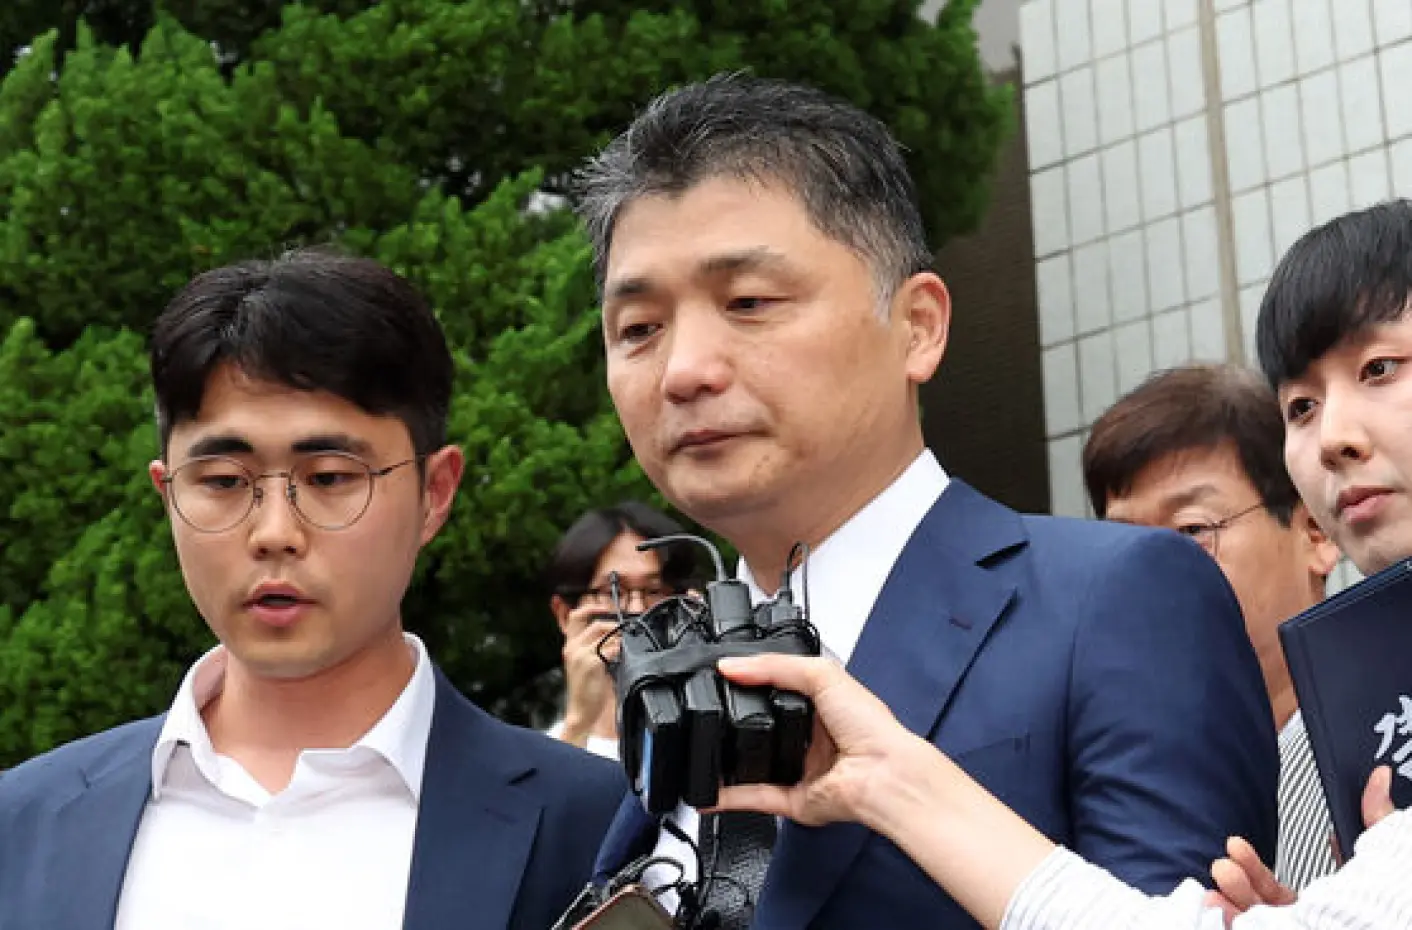
The Kakao founder 15-year sentence request has turned a contested K-pop takeover into a wider test of corporate accountability in South Korea’s technology economy. At the final appellate hearing on Wednesday, prosecutors asked Seoul High Court Criminal Division 4-1 to sentence Kakao founder Kim Beom-su, also known as Brian Kim, to 15 years in prison, impose a ₩510 million fine—about $377,000—and confiscate approximately ₩127.2 billion, according to Aju Press.
The request is not a judgment. Kim was acquitted at the first trial in 2025, denies directing illegal conduct and remains legally innocent unless a court convicts him. Prosecutors are asking Judges Kim In-gyeom, Seong Ji-yong and Jeon Ji-won to overturn that result, arguing the lower court made “errors of fact and misunderstandings of law” and failed to give proper weight to evidence they regard as clear.
The Seoul High Court has not set a date for its ruling. Whichever side loses is likely to seek review by South Korea’s Supreme Court, although a further appeal cannot be treated as certain until it is filed.
What prosecutors asked the court to do
The requested sentence for Kim matches what prosecutors sought at the first trial: 15 years in prison and a ₩510 million fine. For Bae Jae-hyun, the former head of Kakao’s investment division, they requested 12 years and the same ₩510 million fine. Kakao and Kakao Entertainment, charged as corporate defendants, each face a requested fine of ₩500 million.
The largest financial demand is separate from those fines. Prosecutors asked for about ₩127.2 billion to be confiscated from Kim. Confiscation is designed to remove alleged proceeds or economic benefit connected to an offense; a fine is punishment. The two figures therefore serve different legal purposes, even though both would impose financial consequences if ordered.
That distinction explains the apparent imbalance. The confiscation request is roughly 249 times the ₩510 million fine. The prosecution’s theory is not that the fine alone should represent the scale of the alleged transaction. It is that imprisonment supplies the main punitive force, the fine adds a monetary penalty, and confiscation prevents retention of value prosecutors connect to the alleged scheme. The defense disputes the underlying crime, so it necessarily contests the premise for all three.
The prosecution’s manipulation theory
The case concerns February 2023, when HYBE launched a tender offer for shares of SM Entertainment at ₩120,000 apiece. Prosecutors allege that Kakao, working with private-equity firm One Asia Partners, used large share purchases and high-priced buy orders to keep SM’s market price above that level. If shares could be sold in the market for more than HYBE’s offer, investors had less reason to tender them, making the ₩120,000 line commercially decisive.
On that theory, the price threshold was not simply a valuation target. It was the operational point at which trading could frustrate a rival’s offer. Prosecutors cited KakaoTalk conversations about blocking the tender offer and instructions to buy when SM shares fell below ₩120,000. They say individual orders must be assessed alongside the takeover contest and the sequence of transactions, rather than viewed as isolated market purchases.
The allegation remains disputed. A purchase can support a share price without automatically being illegal: acquirers routinely buy strategic stakes, respond to competing bids and revise valuations. The prosecution must therefore prove not merely that Kakao’s buying affected the price, but that the defendants possessed the legally required manipulative purpose and used prohibited methods. That is the core of the Kakao SM Entertainment stock manipulation appeal.
The defense: a normal business move, not a criminal scheme
Kim’s position is that he neither ordered nor tolerated illegal activity. The defense has characterized Kakao’s conduct as a normal business move in an intense acquisition contest, not an artificial attempt to deceive the market. That argument asks the court to distinguish aggressive competition for corporate control from transactions intended to create a false or misleading price.
The 2025 acquittal gives that argument substantial legal weight. An appellate panel does not begin with a conviction to review; prosecutors must persuade it that the trial court’s reading of the evidence and law was wrong. The prosecution says the first court ignored conversations and trading patterns that reveal intent. The defense says lawful commercial purpose explains the same events. Kakao declined to comment on Wednesday’s sentencing request.
Kim was arrested in July 2024 and released on bail in October 2024. Those custody decisions were procedural events, not findings that the allegations were true. His subsequent acquittal is the ruling now before the appellate court.
Critics of aggressive founder prosecutions warn that criminalizing disputed acquisition tactics can make executives excessively cautious, especially when regulators and courts define acceptable conduct only after a fast-moving transaction. That concern deserves consideration. It does not answer whether these particular orders were lawful; it identifies the cost of an unclear boundary.
How a K-pop agency takeover became a criminal case
SM Entertainment’s control battle began as founder Lee Soo-man prepared to exit the company he built. HYBE, home to BTS, agreed to buy Lee’s stake and in February 2023 offered ₩120,000 per share for additional stock. Kakao, seeking a stronger position in music, content and artist distribution, backed SM management and later made a higher counter-offer.
The commercial logic was easy to see. SM controlled a valuable catalog, major artists and a global fan economy. HYBE could deepen its dominance in K-pop production and distribution. Kakao could connect SM’s content to its messaging, entertainment and platform businesses. But the HYBE SM tender offer 2023 also created a clean market test: would enough shareholders sell at ₩120,000?
HYBE’s offer fell short as SM shares traded above the bid price. Kakao eventually secured control. Investigators then asked whether that result flowed from legitimate price discovery and competing strategic demand, or from purchases designed to defeat the tender through artificial price support. The K-pop agency takeover battle became a capital-markets case because the means of winning—not only the final owner—came under scrutiny.
Why this matters for South Korea’s digital elite
South Korea’s corporate-crime narrative has long centered on chaebol families whose industrial groups shaped the postwar economy. Kim represents a newer class of power. He founded Kakao, launched KakaoTalk in 2010 and built the company and its affiliates into one of the country’s defining digital businesses. The KakaoTalk founder trial therefore asks whether capital-markets enforcement reaches platform-era founders with the same intensity associated with legacy conglomerates.
The historical contrast is Samsung Electronics chairman Lee Jae-yong. Lee was convicted in a bribery case tied to former president Park Geun-hye, served prison time and received a presidential pardon in 2022. The cases involve different statutes, evidence and political contexts; they should not be treated as direct sentencing precedents. The comparison matters at the level of institutions: South Korea has repeatedly wrestled with punishing powerful business leaders while worrying about disruption to companies regarded as nationally important.
A conviction here could strengthen the deterrent force of the Capital Markets Act in takeover contests, especially where private messages and order patterns are used together to infer purpose. An acquittal could affirm that prosecutors need clearer proof before converting strategic stock purchases into manipulation. Either outcome would shape advice given to boards, bankers and founders in future control battles.
What the numbers mean
Fifteen years is the clearest signal of prosecutorial severity. It places alleged market manipulation in the realm of major economic crime rather than a technical disclosure violation. But a request is not a forecast. Courts assess statutory ranges, the defendant’s role, intent, harm and precedent, and the first-trial acquittal makes any simple prediction especially unreliable.
₩510 million is modest beside the confiscation demand and the corporate scale of the takeover. That does not make it meaningless; it shows why the prosecution’s package must be read as a whole. Prison, fine and confiscation are cumulative instruments, not substitutes measured on a single scale.
₩127.2 billion makes economic attribution the appeal’s largest financial question. If the court accepts confiscation, it will need a legal basis connecting that amount to the offense. If it rejects the manipulation theory, the foundation for confiscation falls with it. The headline number should therefore not be reported as money already owed.
₩120,000 was the tender-offer threshold around which the alleged conduct is organized. A price above it weakened HYBE’s bid; a price below it made tendering more attractive. The threshold helps explain motive but does not prove manipulation by itself.
Comparisons with past Korean market-manipulation penalties require caution. Outcomes vary with the statute charged, gains attributed, number of defendants, evidence of intent, victim harm and procedural posture. The unusual severity of this request is clear from its own terms; claiming it is a record or directly equivalent to another case would require a matched legal dataset that the available reporting does not provide.
Investors face a governance overhang
Kakao shares fell 1.3% in Seoul trading as of 0524 GMT on Wednesday, Reuters reported. A one-day move cannot establish why every investor traded, but the appeal adds a measurable governance overhang. A conviction could constrain Kim’s leadership, revive succession questions and increase pressure on the board to show operational independence from the founder. An acquittal would reduce immediate legal risk without erasing scrutiny of how Kakao approved and supervised the SM transaction.
The corporate fines sought from Kakao and Kakao Entertainment are small relative to the scale of their businesses. Their significance is reputational and institutional: a corporate conviction would say the alleged conduct was not merely the unauthorized act of individuals. It could affect compliance systems, board accountability and the credibility of management assurances to shareholders.
That issue connects to broader technology governance. Our coverage of Google’s Irish privacy fine examines how regulators test the gap between visible controls and corporate practice. The Binance sanctions investigation similarly shows that platform scale increases, rather than eliminates, the demand for traceable decisions. And BitMEX’s closure illustrates how legal history and competitive decline can outlast a founder’s original innovation.
K-pop consolidation has its own stakes
For the music industry, the appeal is about more than one share chart. HYBE and Kakao approached SM with competing visions of consolidation. One emphasized a larger music-company portfolio; the other joined content ownership to a sprawling digital platform. Both raised questions about bargaining power over artists, distribution, fan services and smaller agencies.
A conviction would not automatically unwind Kakao’s ownership of SM, but it could complicate future acquisitions and strengthen calls for closer review of how major platforms buy cultural assets. An acquittal could reassure dealmakers that market purchases during takeover contests remain permissible when supported by genuine investment objectives. Neither outcome settles whether consolidation benefits artists or fans; it changes the legal risk attached to pursuing it.
What happens next
The appellate panel will first decide whether the trial court made the factual or legal errors alleged by prosecutors. It could affirm the acquittal, convict on some or all charges, or reach a mixed result across defendants. Because the ruling date has not been set, any claim that judgment is imminent would go beyond the record.
A Supreme Court appeal is the most likely next stage after a decisive loss, given the stakes for Kim, the companies and prosecutors, but the scope of review would depend on the appellate judgment. Meanwhile, Kakao’s board must plan for more than one outcome: continued founder leadership after acquittal, temporary or lasting limits after conviction, and a prolonged period in which legal uncertainty affects strategic decisions.
For Korean technology companies, the lasting question is whether the case produces a clearer rule. Founders need freedom to compete, invest and make bids; markets need protection from orders designed to manufacture price signals. The court’s task is not to choose between innovation and enforcement in the abstract. It is to decide, on evidence, which side of that line Kakao’s 2023 conduct occupied.
Sources: Reuters, citing Yonhap News Agency; Seoul Economic Daily; Aju Press; K-POPIT. Established facts are attributed above; charges remain allegations, Kim denies wrongdoing and the first court acquitted him.